
how to calculate value of pension for net worth

Estimated Net Worth
$1.2 Million
Calculating the value of a pension for net worth is a key part of understanding financial health, especially for those with long-term retirement benefits. Pensions can be a major asset, but their value isn’t always straightforward to determine. Unlike liquid assets like cash or stocks, pensions provide future income, which requires estimation and projection. Whether you’re assessing your own financial standing or analyzing someone else’s, knowing how to factor in pension value is essential for an accurate net worth calculation.
This article breaks down the process step by step, covering how to estimate pension worth, its role in overall net worth, and other financial factors to consider. We’ll look at the components that influence pension valuation, how to account for them, and how they fit into a broader financial picture. By the end, you’ll have a clear method for including pensions in net worth assessments.
How to Calculate Value of Pension for Net Worth in 2026
To calculate the value of a pension for net worth in 2026, you first need to determine its present value. Pensions are future income streams, so their worth today depends on factors like expected payouts, life expectancy, and discount rates. The most common method is the present value calculation, which adjusts future payments to today’s dollars. For example, if a pension pays $50,000 annually starting at age 65, you’d discount those payments back to the current year using an appropriate interest rate.
Another approach is the lump-sum equivalent, which some pension plans offer as an option. If the plan allows a one-time payout instead of monthly checks, that amount can be directly added to net worth. However, not all pensions provide this choice, so the present value method is often necessary. Online calculators or financial software can simplify this process, but understanding the underlying math ensures accuracy.
It’s also important to consider whether the pension is defined benefit or defined contribution. Defined benefit plans guarantee specific payouts, making valuation more predictable. Defined contribution plans, like 401(k)s, depend on market performance, so their value fluctuates. For net worth purposes, defined benefit pensions are easier to quantify, while defined contribution plans require current balance checks.
Career and Beginnings
A pension’s value is closely tied to the career that earned it. The length of service, salary history, and employer contributions all play a role in determining payouts. For someone with a long career in a high-paying industry, the pension could be substantial. Public sector employees, for example, often have pensions based on years of service and final salary, leading to significant retirement income.
Early career decisions also impact pension value. Switching jobs frequently can reduce pension benefits if vesting periods aren’t met. Some pensions require a minimum number of years before benefits are fully earned, so job stability is a factor. Understanding the rules of a specific pension plan is crucial for accurate valuation.
For those with multiple pensions from different employers, each one must be evaluated separately. Some plans may have cost-of-living adjustments, while others remain fixed. The total pension value is the sum of all individual pensions, adjusted for their unique terms. This requires gathering statements or estimates from each plan administrator.
Business Ventures & Assets
Pensions are just one part of a broader asset portfolio. Business ventures, real estate, and investments also contribute to net worth. When calculating net worth, pensions should be considered alongside these other assets. For instance, if someone owns a business, its value must be appraised separately and added to the pension’s present value.
Real estate is another major asset that affects net worth. The equity in a home, rental properties, or commercial buildings should be included. Unlike pensions, real estate values can be volatile, so regular appraisals are necessary. Combining these assets with pension value gives a complete financial picture.
Other assets like stocks, bonds, and retirement accounts also factor into net worth. Defined contribution plans, such as 401(k)s or IRAs, are easier to value since they have a current balance. However, they should still be considered alongside pensions for a full assessment. The goal is to account for all income-generating assets, not just pensions.
Earnings and Income Streams
Pensions are a form of deferred income, but they’re not the only income stream in retirement. Social Security, rental income, dividends, and part-time work can all supplement pension payments. When calculating net worth, these additional income sources should be considered, though they’re not always included in the pension’s value.
For those still working, current earnings also affect net worth. A high salary can lead to larger pension contributions, increasing future benefits. Some pensions are calculated based on final average salary, so career earnings directly impact pension value. This is why salary growth over time matters for accurate projections.
It’s also worth noting that pensions may have survivor benefits. If a pension includes payments to a spouse after the pensioner’s death, that value should be factored into net worth. This requires estimating the likelihood and duration of survivor payments, which adds another layer to the calculation. Understanding all income streams ensures a realistic net worth assessment.
Frequently Asked Questions About how to calculate value of pension for net worth
1. How do I calculate the value of my pension for my net worth in 2026?
To calculate the value of your pension for your net worth in 2026, you can use one of the following methods:
– Present Value (PV) Method: Estimate the future income stream from your pension and discount it back to today’s dollars using a reasonable discount rate (e.g., 4-6%).
– Lump-Sum Equivalent: If your pension offers a lump-sum payout option, use that amount as the value.
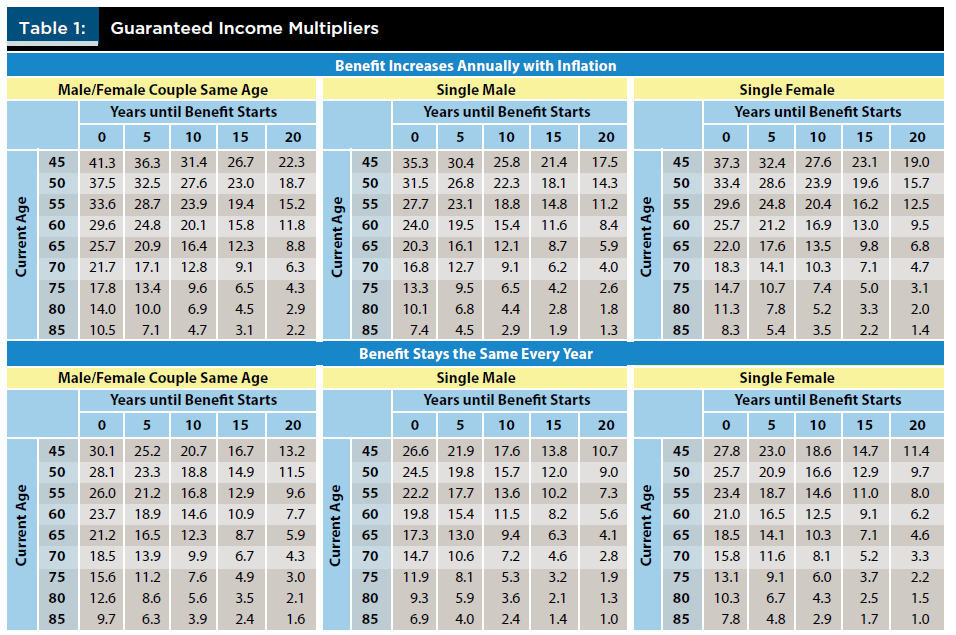
– Annuity Purchase Price: Determine how much it would cost to buy an equivalent annuity in the current market.
– Rule of Thumb: Some financial planners suggest multiplying your annual pension benefit by 10-20x for a rough estimate.
2. Should I include my pension in my net worth calculation for 2026?
Yes, including your pension in your net worth provides a more accurate financial picture. However, since pensions are future income streams, they should be valued conservatively. Treat them as an asset but recognize that their value depends on factors like inflation, pension stability, and payout terms.
3. What discount rate should I use to calculate the present value of my pension in 2026?
A common approach is to use a discount rate between 4% and 6%. A lower rate (e.g., 4%) assumes more conservative growth, while a higher rate (e.g., 6%) reflects a riskier or higher-return scenario. Some people use the current 10-year Treasury yield or their expected investment return rate as a benchmark.
4. How do I account for inflation when valuing my pension for net worth in 2026?
If your pension has cost-of-living adjustments (COLA), factor those into your calculations. If not, adjust the future payments downward to reflect inflation (e.g., assume a 2-3% annual inflation rate). For example, if your pension pays $50,000/year in 2026, its purchasing power in 20 years may be closer to $30,000–$40,000 in today’s dollars.
5. Is the value of a defined benefit (DB) pension different from a defined contribution (DC) plan for net worth purposes?
Yes. A defined benefit (DB) pension guarantees a specific payout, so you’d calculate its present value based on future payments. A defined contribution (DC) plan (e.g., 401(k)) is already a tangible asset—its value is simply the current balance, so no additional calculation is needed.
6. How do I value a pension that hasn’t started paying out yet in 2026?
For a pension that hasn’t begun, estimate the future payout based on your plan’s formula (e.g., years of service × multiplier × final salary). Then, discount those future payments back to 2026 using a present value calculation. Online pension calculators or financial advisors can help with this.
7. What if my pension is from a government or employer that might reduce benefits?
If there’s risk of benefit cuts (e.g., underfunded pension plans), apply a “haircut” to the value. For example, reduce the estimated payout by 10-30% to account for potential reductions. Alternatively, use a higher discount rate to reflect the added risk.
8. Can I use the cash balance of my pension plan as its net worth value in 2026?
If your pension is a cash balance plan, you can use the current balance as its value since it’s similar to a defined contribution plan. However, if it’s a traditional defined benefit plan, you’ll need to calculate the present value of future payments instead.
9. How does Social Security differ from a pension in net worth calculations for 2026?
Social Security is a government benefit, not an employer pension, so it’s typically excluded from net worth calculations. However, if you want to include it, you can estimate its present value using the same discounting methods as a pension—but be aware that Social Security is subject to political and economic risks.
10. Are there online tools or calculators to help value my pension for net worth in 2026?
Yes, several tools can help:
– Pension Present Value Calculators (e.g., from financial planning websites).
– Annuity Purchase Calculators (to estimate lump-sum equivalents).
– Retirement Planning Software (e.g., Personal Capital, Fidelity’s retirement tools).
– Spreadsheet Formulas (e.g., Excel’s PV function for manual calculations). Always cross-check results with a financial advisor for accuracy.
