
net worth goals by age

Estimated Net Worth
$1.9 Million
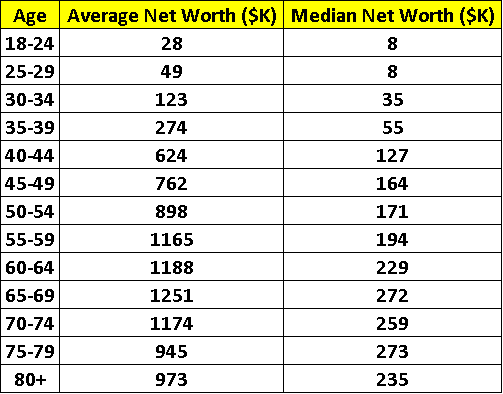
Net worth goals by age are a practical way to measure financial progress, whether you’re just starting out or well into your career. The idea isn’t about comparing yourself to others but about setting realistic benchmarks based on income, savings, investments, and lifestyle choices. While some people focus on aggressive wealth accumulation, others prioritize stability, debt freedom, or passive income. The key is understanding where you stand relative to your age group and adjusting your strategy accordingly. Financial milestones aren’t one-size-fits-all, but having a framework helps keep long-term goals in sight.
For those looking to build wealth, net worth targets by age can serve as checkpoints rather than rigid rules. Early career stages often involve paying off debt and establishing savings, while later years may shift toward investment growth and asset accumulation. The numbers vary depending on profession, location, and personal circumstances, but the principles remain consistent: spend less than you earn, invest wisely, and avoid unnecessary liabilities. Whether you’re aiming for financial independence or simply a comfortable retirement, tracking net worth by age provides clarity on what’s working—and what needs adjustment.
Net Worth Goals by Age in 2026
Net worth benchmarks by age in 2026 reflect a mix of economic conditions, career trajectories, and personal financial habits. For someone in their 20s, a modest but positive net worth—even if just a few thousand dollars—is a solid start, considering student loans and entry-level salaries. By 30, many aim for a net worth equal to their annual income, though this varies widely based on education, industry, and location. Those in high-earning fields like tech or finance may surpass this, while others in lower-paying professions might take longer to hit the mark.
In the 40s, the target often shifts to three to five times annual income, as earnings typically peak and retirement savings become a priority. Homeownership, investment portfolios, and business equity play larger roles at this stage. By 50, the focus turns to six to eight times annual income, with many aiming for a net worth that supports a comfortable retirement. These benchmarks aren’t absolute but serve as guidelines to assess whether savings and investments are on track. The numbers adjust for inflation, market performance, and individual lifestyle choices.
Career and Beginnings
Most people’s net worth journey starts with their first job, where income is often modest but foundational. Early career stages involve building skills, increasing earning potential, and establishing financial habits like budgeting and saving. For many, the first decade of work is about balancing debt repayment—student loans, credit cards—with starting an emergency fund. Those who prioritize saving even small amounts early benefit from compound growth over time. Entry-level salaries may not allow for rapid wealth accumulation, but consistent contributions to retirement accounts and avoiding lifestyle inflation set the stage for future growth.
Career progression plays a major role in net worth expansion. Moving into higher-paying roles, switching industries, or pursuing advanced degrees can accelerate earnings. Some choose stability in corporate jobs, while others take risks with entrepreneurship or freelancing. The key is aligning career choices with financial goals. For example, someone in a high-demand field like healthcare or engineering may reach net worth milestones faster than someone in a lower-paying creative profession. Early career decisions—like negotiating salaries, relocating for better opportunities, or investing in further education—have long-term effects on net worth.
Business Ventures & Assets
Assets are the cornerstone of net worth, and business ventures often become a significant driver of wealth. For those who start or invest in businesses, equity can grow exponentially if the venture succeeds. Even small side hustles or freelance work can contribute to net worth by generating additional income streams. Real estate is another common asset, with homeownership often being the first major purchase. Rental properties, commercial real estate, or REITs can further diversify an asset portfolio. The key is acquiring assets that appreciate or generate passive income rather than liabilities that drain resources.
Investments outside of business and real estate also play a crucial role. Stocks, bonds, mutual funds, and retirement accounts like 401(k)s and IRAs are standard components of a balanced portfolio. The earlier someone starts investing, the more time their money has to grow. Some opt for aggressive growth strategies in their 20s and 30s, shifting to more conservative allocations as they near retirement. Others focus on alternative investments like cryptocurrency, private equity, or collectibles, though these carry higher risk. The goal is to build a diversified asset base that aligns with risk tolerance and long-term financial objectives.
Earnings and Income Streams
Primary income from a job or business is the most common way people build net worth, but relying on a single source is risky. Diversifying income streams—through side gigs, investments, or passive revenue—provides financial security and accelerates wealth growth. For example, someone with a full-time job might also earn rental income, dividends, or royalties from creative work. High earners often maximize their primary income first, then reinvest surplus funds into assets that generate additional cash flow. The more income streams someone has, the faster their net worth can grow.
Earnings potential varies widely by industry, education, and experience. Those in lucrative fields like medicine, law, or technology often have higher base salaries, allowing for faster net worth accumulation. Others may need to supplement their income with freelance work, consulting, or part-time businesses. The gig economy has made it easier to generate extra income, whether through ride-sharing, online tutoring, or selling digital products. The key is to ensure that additional income streams don’t come at the expense of primary career growth or personal well-being. Balancing multiple income sources requires discipline but can significantly boost net worth over time.
Frequently Asked Questions About net worth goals by age
1. What is a good net worth goal by age 30 in 2026?
A common benchmark is to aim for a net worth equal to your annual salary by age 30. For example, if you earn $60,000 per year, a net worth of $60,000 (including savings, investments, and assets minus debts) is a solid goal. This helps set a foundation for long-term financial growth.
2. How much should I have saved by age 40 in 2026?
By age 40, financial experts often recommend having a net worth of about 2–3 times your annual salary. If you earn $100,000, a net worth of $200,000–$300,000 (including retirement accounts, home equity, and other assets) is a reasonable target.
3. What is the average net worth for someone in their 50s in 2026?
The average net worth for individuals in their 50s varies widely, but a general guideline is to have 5–7 times your annual income saved. For example, if you earn $120,000, a net worth of $600,000–$840,000 (including retirement savings and other assets) is a strong position.
4. How much should I have saved for retirement by age 60 in 2026?
By age 60, many financial advisors suggest having 8–10 times your annual salary saved for retirement. If you earn $150,000, a net worth of $1.2–$1.5 million (including 401(k)s, IRAs, and other investments) can help ensure a comfortable retirement.
5. Is it realistic to become a millionaire by age 50 in 2026?
Yes, it’s achievable with disciplined saving, investing, and smart financial planning. Starting early, maximizing retirement contributions, and investing in appreciating assets (like stocks or real estate) can help you reach a $1 million net worth by 50.
6. What net worth should I aim for by age 35 in 2026?
A common target is to have 1–1.5 times your annual salary saved by age 35. For instance, if you earn $80,000, a net worth of $80,000–$120,000 (including savings, investments, and home equity) is a good benchmark.
7. How does debt affect my net worth goals by age?
Debt (like student loans, mortgages, or credit card balances) reduces your net worth. To stay on track, prioritize paying off high-interest debt while building assets. A healthy net worth accounts for both liabilities and assets.
8. What’s a good net worth goal for someone in their 20s in 2026?
In your 20s, focus on building an emergency fund (3–6 months of expenses) and starting retirement savings. A net worth of $10,000–$50,000 (depending on income and expenses) is a solid early goal.
9. How can I calculate my net worth to track progress in 2026?
To calculate net worth, subtract your total liabilities (debts) from your total assets (savings, investments, property, etc.). Use a spreadsheet or financial app to track changes over time and adjust your goals accordingly.
10. Are net worth goals different for high earners vs. average earners in 2026?
Yes, net worth goals scale with income. High earners may aim for higher multiples of their salary (e.g., 10x by retirement), while average earners focus on steady growth. Adjust benchmarks based on your income, lifestyle, and financial priorities.
