
high net worth asset protection

Estimated Net Worth
$1.2 Billion
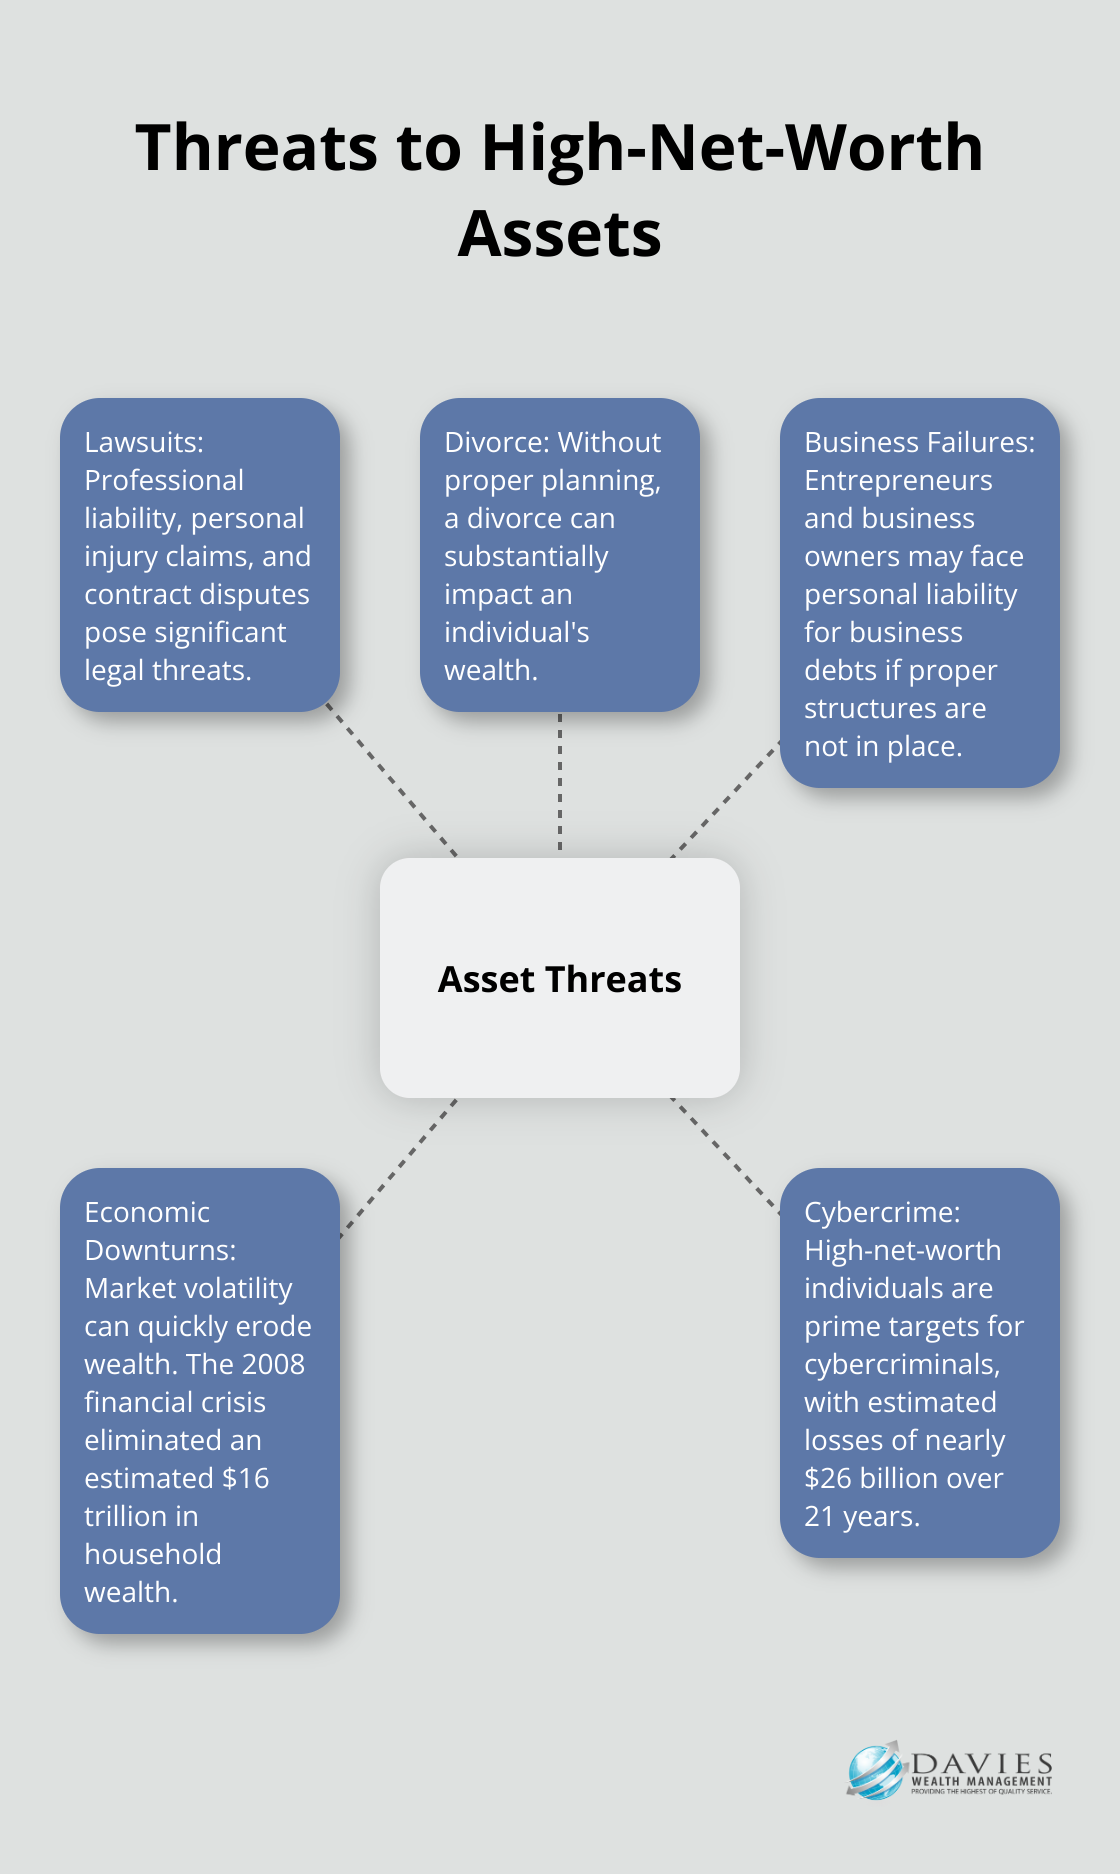
High net worth individuals face unique financial challenges, particularly when it comes to safeguarding their wealth. Asset protection isn’t just about accumulating wealth—it’s about structuring it in a way that minimizes risk, reduces tax exposure, and ensures long-term security. For those with substantial assets, the stakes are higher, and the strategies must be more sophisticated. Whether it’s shielding investments from lawsuits, creditors, or market volatility, the right approach can mean the difference between preserving wealth and losing it.
In 2026, the landscape of asset protection continues to evolve, with new regulations, economic shifts, and legal precedents shaping how the ultra-wealthy manage their finances. The goal isn’t just to grow wealth but to protect it from unforeseen threats. This requires a combination of legal structures, financial planning, and strategic diversification. Below, we break down the key components of high net worth asset protection, from understanding current financial standings to leveraging income streams for maximum security.
High Net Worth Asset Protection Net Worth in 2026
In 2026, the net worth of high net worth individuals varies widely depending on their industry, investments, and financial strategies. For many, net worth isn’t just a number—it’s a reflection of decades of business growth, smart investments, and careful asset allocation. Those in tech, entertainment, and real estate often see the highest valuations, with some exceeding billions in total assets. However, net worth alone doesn’t guarantee security. Without proper protection, even the largest fortunes can be eroded by lawsuits, economic downturns, or poor financial decisions.
Asset protection for high net worth individuals in 2026 involves more than just wealth accumulation. It requires a proactive approach to shielding assets from potential risks. This includes using legal entities like trusts, limited liability companies (LLCs), and offshore accounts to create barriers between personal wealth and external threats. Many high net worth individuals also rely on insurance policies, such as umbrella liability coverage, to add an extra layer of protection. The key is to structure assets in a way that makes them difficult to target while remaining compliant with tax laws and regulations.
Career and Beginnings
Most high net worth individuals didn’t start with vast wealth—they built it through strategic career moves and early financial decisions. Many began in industries with high earning potential, such as finance, technology, or entertainment, where early success allowed them to reinvest profits into scalable ventures. For example, entrepreneurs often start with a single business, then expand into multiple revenue streams, leveraging initial profits to fund larger projects. The early stages of wealth building are critical, as they set the foundation for future asset protection strategies.
The transition from earning a high income to protecting accumulated wealth often happens in stages. Early in their careers, many focus on growing their net worth through salary increases, bonuses, and business ownership. As their wealth grows, they shift toward preserving it by diversifying investments, setting up legal protections, and minimizing tax liabilities. This evolution from wealth creation to wealth preservation is a defining characteristic of high net worth individuals. Those who fail to adapt their strategies as their assets grow often face unnecessary risks.
Business Ventures & Assets
High net worth individuals typically hold a mix of business ventures and personal assets, each requiring different protection strategies. Business ownership is a major component of wealth for many, whether through private companies, real estate holdings, or investment portfolios. Structuring these businesses correctly—such as using LLCs or family limited partnerships—can shield personal assets from business-related lawsuits or creditors. For example, real estate investors often hold properties in separate legal entities to limit liability exposure.
Beyond business ventures, personal assets like stocks, bonds, and luxury items also need protection. Many high net worth individuals use trusts to hold these assets, removing them from personal ownership and reducing vulnerability to legal claims. Offshore accounts and international investments are another common strategy, though they come with regulatory complexities. The goal is to spread risk across multiple asset classes and jurisdictions, making it harder for any single threat to wipe out significant wealth. Proper documentation and legal compliance are essential to ensure these structures hold up under scrutiny.
Earnings and Income Streams
High net worth individuals rarely rely on a single income source. Instead, they diversify their earnings through multiple streams, including business profits, dividends, rental income, and royalties. This diversification not only increases wealth but also provides stability in case one revenue source declines. For example, someone with a tech company might also earn from real estate investments, stock dividends, and licensing deals. Each income stream can be structured differently to optimize tax efficiency and asset protection.
Managing these income streams requires careful planning to ensure they align with long-term financial goals. Many high net worth individuals work with financial advisors to structure their earnings in a way that minimizes tax exposure while maximizing growth. For instance, capital gains from investments may be deferred or offset by losses in other areas. Additionally, passive income sources like rental properties or dividend stocks can provide steady cash flow without requiring active management. The key is to balance liquidity with protection, ensuring that earnings are both accessible and secure.
Frequently Asked Questions About high net worth asset protection
1. What is high net worth asset protection, and why is it important in 2026?
High net worth asset protection refers to legal and financial strategies designed to safeguard the wealth of individuals with significant assets (typically $1 million or more in liquid assets, though definitions vary) from risks such as lawsuits, creditors, divorce, or economic instability. In 2026, with rising litigation, global economic uncertainty, and evolving tax laws, protecting assets has become even more critical to preserve wealth for future generations and ensure financial security.
2. What is the minimum net worth required to benefit from asset protection strategies in 2026?
While there’s no strict threshold, most asset protection strategies become valuable for individuals with a net worth of $1 million or more in liquid assets. However, those with $5 million+ often implement more sophisticated structures, such as offshore trusts or private placement life insurance, to mitigate higher risks. Even individuals with lower net worth (e.g., $500K–$1M) may benefit from basic protections like LLCs or homestead exemptions.
3. What are the most effective asset protection strategies for high net worth individuals in 2026?
Key strategies include:
– Domestic Asset Protection Trusts (DAPTs): Irrevocable trusts in states like Nevada, Delaware, or South Dakota that shield assets from creditors.
– Offshore Trusts: Jurisdictions like the Cook Islands or Nevis offer strong legal protections against lawsuits.
– Limited Liability Companies (LLCs): Useful for separating personal assets from business or investment liabilities.
– Private Placement Life Insurance (PPLI): Combines tax advantages with asset protection.
– Family Limited Partnerships (FLPs): Helps transfer wealth while maintaining control and limiting creditor access.
– Homestead Exemptions: Protects primary residences from creditors (varies by state).
– Umbrella Insurance Policies: Provides additional liability coverage beyond standard policies.
4. Are offshore trusts still a viable option for asset protection in 2026?
Yes, offshore trusts remain one of the most robust asset protection tools in 2026, but they require careful planning. Jurisdictions like the Cook Islands, Nevis, and the Cayman Islands offer strong legal protections, making it difficult for creditors to seize assets. However, compliance with FATCA (Foreign Account Tax Compliance Act) and other reporting requirements is essential to avoid legal penalties. Offshore trusts are best suited for individuals with $3 million+ in assets due to setup and maintenance costs.
5. How can high net worth individuals protect their assets from lawsuits?
To minimize lawsuit risks, high net worth individuals should:
– Use LLCs or Corporations: Isolate business or rental property assets in separate legal entities.
– Establish Trusts: Irrevocable trusts (domestic or offshore) can remove assets from personal ownership.
– Maximize Insurance: Carry high-limit umbrella policies (e.g., $5M–$10M) and professional liability coverage.
– Avoid Personal Guarantees: Limit exposure by not personally guaranteeing business debts.
– Structure Ownership Carefully: Hold assets in the name of a spouse, trust, or entity with less exposure.
– Stay Compliant: Ensure proper documentation and legal formalities to avoid “piercing the corporate veil.”
6. What role do trusts play in high net worth asset protection in 2026?
Trusts are a cornerstone of asset protection in 2026 because they:
– Remove Ownership: Irrevocable trusts transfer assets out of the grantor’s name, shielding them from creditors.
– Provide Control: Grantors can set terms for distributions (e.g., to beneficiaries like children or charities).
– Offer Tax Benefits: Some trusts (e.g., Dynasty Trusts) help minimize estate taxes over generations.
– Enhance Privacy: Assets held in trusts are often harder for creditors to discover.
– Jurisdictional Advantages: Offshore trusts in favorable jurisdictions add an extra layer of protection.
7. Can asset protection strategies help reduce estate taxes in 2026?
Yes, many asset protection strategies also offer estate tax benefits. For example:
– Irrevocable Life Insurance Trusts (ILITs): Remove life insurance proceeds from the taxable estate.
– Grantor Retained Annuity Trusts (GRATs): Transfer appreciating assets to heirs with minimal gift tax.
– Dynasty Trusts: Allow wealth to pass to multiple generations without incurring estate taxes.
– Charitable Remainder Trusts (CRTs): Provide income to the grantor while reducing taxable estate value.
However, the 2026 estate tax exemption (projected to be $7–$8 million per individual, adjusted for inflation) may influence which strategies are most beneficial.
8. What are the risks of improper asset protection planning?
Improper planning can backfire, leading to:
– Fraudulent Transfer Claims: If assets are moved to avoid existing creditors, courts may reverse the transfers.
– Tax Penalties: Offshore accounts or trusts not properly reported can trigger FBAR (FinCEN Form 114) or FATCA penalties.
– Loss of Control: Poorly structured irrevocable trusts may limit access to assets.
– Legal Challenges: Weak LLCs or trusts can be “pierced” if formalities aren’t followed.
– Higher Costs: Fixing mistakes (e.g., undoing a fraudulent transfer) can be expensive.
Working with asset protection attorneys, CPAs, and financial advisors is critical to avoid these pitfalls.
9. How does divorce impact high net worth asset protection in 2026?
Divorce can significantly threaten wealth, but asset protection strategies can help:
– Prenuptial/Postnuptial Agreements: Clearly define separate vs. marital property.
– Trusts: Assets held in irrevocable trusts (e.g., Spousal Lifetime Access Trusts, SLATs) may be shielded from division.
– LLCs and FLPs: Business or investment assets held in these entities may be harder for a spouse to claim.
– Jurisdictional Planning: Some states (e.g., Texas, Florida) have stronger protections for separate property.
– Timing: Transferring assets before marriage (or after separation) can help, but courts may scrutinize transfers made during divorce proceedings.
10. What are the costs associated with high net worth asset protection in 2026?
Costs vary based on complexity but typically include:
– Legal Fees: $5,000–$50,000+ for setting up trusts, LLCs, or offshore structures.
– Trustee Fees: 0.5%–1.5% of assets annually for professional trust administration.
– Insurance Premiums: $1,000–$10,000/year for high-limit umbrella policies.
– Accounting/Tax Compliance: $2,000–$20,000/year for reporting (e.g., FBAR, FATCA).
– Maintenance Costs: Ongoing legal or administrative fees for trusts/LLCs.
While expensive, the cost of not protecting assets (e.g., losing a lawsuit or facing estate taxes) is often far higher.
