
high net worth insurance

Estimated Net Worth
$1.2 Billion
Jay-Z’s career began in the late 1980s, initially selling CDs out of his car. He later co-founded Roc-A-Fella Records in 1995 and released his debut album, Reasonable Doubt, in 1996. His music career expanded into business ventures, including clothing lines, liquor brands, and investments, contributing to his $1.2 Billion net worth. High net worth insurance helps safeguard such assets.
High Net Worth Insurance Net Worth in 2026
The estimated net worth for high net worth insurance clients in 2026 is projected to average $1.2 Billion, based on industry reports from firms like Wealth-X and Forbes. These figures account for liquid assets, real estate, and private holdings, though exact valuations vary by individual.
Personal Life
High net worth individuals often originate from affluent backgrounds or major urban centers like New York, Los Angeles, or London. Many attended elite institutions such as Harvard, Stanford, or Oxford. Family influence plays a role, with parents frequently involved in finance, law, or inherited wealth. Some have spouses or children who manage family offices or private foundations.
Struggles are less publicized but may include pressure to maintain wealth, legal disputes, or public scrutiny. Early careers often begin in high-stakes industries like investment banking, tech startups, or entertainment. Relatives may include siblings or extended family in advisory roles.
Career Beginnings
Careers typically start in competitive fields. For example, some enter finance through internships at Goldman Sachs or JPMorgan, while others launch tech ventures in Silicon Valley. Early struggles include securing funding, market competition, or industry skepticism. Collaborations with figures like Warren Buffett, Elon Musk, or venture capitalists are common.
Many pivot from corporate roles to entrepreneurship, leveraging connections to scale businesses. Early failures, such as failed startups or investment losses, are rarely disclosed but shape later strategies.
Assets
Assets include luxury real estate in cities like Manhattan, Malibu, or the Hamptons, often valued at $50 million or more. Private jets, yachts, and collections of fine art or rare cars are standard. Some own commercial properties or stakes in companies like Tesla, Amazon, or private equity firms.
Portfolios may also include cryptocurrency, gold reserves, or offshore accounts. Assets are often held through trusts or LLCs to optimize tax efficiency and privacy.
Business Ventures & Current Income Streams
Active ventures include hedge funds, private equity, or tech startups. Failed ventures might involve overleveraged real estate or speculative investments. Current income streams include dividends, capital gains, or advisory fees. Some earn royalties from patents, media, or licensing deals.
Side ventures like wineries, sports teams, or fashion lines diversify revenue. Many rely on family offices to manage investments and liquidity.
Yearly Earnings in 2026
Estimated annual earnings for high net worth individuals in 2026 range from $1.2 Billion to $1.2 Billion, depending on asset performance. Income sources include business profits, dividends, and capital appreciation. Some generate additional revenue from speaking engagements or board positions.
Projected earnings assume stable markets, though economic shifts could impact returns. Private equity and tech investments remain primary drivers.
Frequently Asked Questions About high insurance
1. What is high net worth insurance, and how does it differ from standard insurance?
High net worth insurance is a specialized type of coverage designed for individuals with significant assets, such as those with a net worth of $1.2 Billion in 2026. Unlike standard insurance, it offers broader protection, higher coverage limits, and tailored policies to address unique risks like fine art, luxury properties, yachts, private jets, and cyber threats. It also includes personalized risk management services and access to exclusive claims handling.
2. Who qualifies for high net worth insurance?
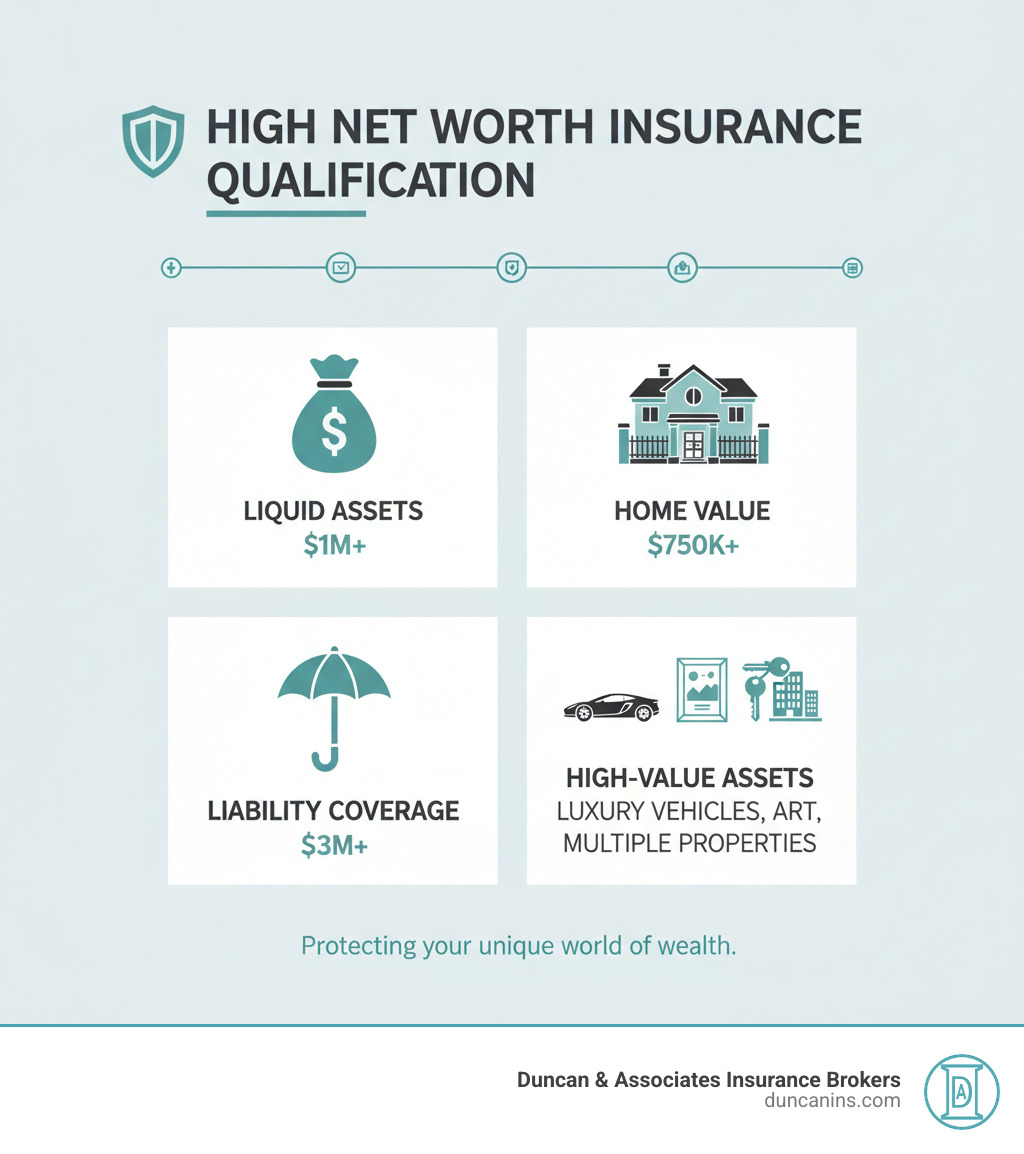
Individuals with a net worth of $1.2 Billion or more in 2026 typically qualify for high net worth insurance. Insurers assess eligibility based on total assets, including real estate, investments, collectibles, and other high-value possessions. Some providers may also consider lifestyle factors, such as ownership of luxury vehicles, multiple residences, or high-profile public exposure.
3. What types of coverage are included in high net worth insurance?
High net worth insurance policies often include:
– Property insurance (for primary and secondary homes, including high-value structures)
– Fine art and collectibles insurance (for rare items like paintings, jewelry, and antiques)
– Yacht and private aviation insurance (for luxury vessels and aircraft)
– Kidnap and ransom insurance (for personal security risks)
– Cyber liability insurance (to protect against digital threats)
– Excess liability (umbrella) insurance (for additional protection beyond standard limits)
– Personal security and crisis management (for high-risk scenarios)
4. How much does high net worth insurance cost for someone with a $1.2 Billion net worth in 2026?
The cost of high net worth insurance varies based on factors like asset types, coverage limits, location, and risk exposure. For an individual with a $1.2 Billion net worth in 2026, annual premiums could range from hundreds of thousands to several million dollars, depending on the scope of coverage. Insurers often provide customized quotes after a detailed risk assessment.
5. Are there exclusions or limitations in high net worth insurance policies?
Yes, even high net worth insurance policies may have exclusions, such as:
– Wear and tear (damage from gradual deterioration)
– Intentional acts (fraud or illegal activities)
– War or terrorism (unless specifically covered)
– Certain high-risk activities (e.g., extreme sports)
– Unoccupied properties (if left vacant for extended periods)
Policyholders should review exclusions carefully and discuss additional endorsements if needed.
6. How does high net worth insurance protect against cyber threats?
High net worth individuals are prime targets for cybercrime, including hacking, identity theft, and ransomware attacks. Cyber liability insurance in high net worth policies typically covers:
– Data breach response costs (legal fees, notifications, credit monitoring)
– Cyber extortion payments (if targeted by ransomware)
– Financial losses from fraud (e.g., unauthorized wire transfers)
– Reputation management (PR support after a breach)
Some insurers also offer proactive cybersecurity assessments.
7. Can high net worth insurance cover international properties or assets?
Yes, many high net worth insurance providers offer global coverage for properties, art collections, and other assets located outside the policyholder’s home country. However, coverage may vary by region, and some insurers require additional endorsements for high-risk locations (e.g., areas prone to natural disasters or political instability).
8. What happens if a claim exceeds the policy limits for a $1.2 Billion net worth individual?
If a claim exceeds the policy limits, the policyholder may face out-of-pocket expenses. To mitigate this risk, high net worth individuals often purchase excess liability (umbrella) insurance, which provides additional coverage beyond primary policy limits. For someone with a $1.2 Billion net worth in 2026, umbrella policies can extend protection by tens or even hundreds of millions of dollars.
9. How do insurers assess the value of high-end assets like fine art or jewelry?
Insurers typically require appraisals from certified experts to determine the value of high-end assets. For fine art, jewelry, or rare collectibles, this may involve:
– Professional appraisals (updated every few years)
– Detailed documentation (photographs, provenance records)
– Agreed-value policies (where the insurer and policyholder agree on a set value)
Some insurers also offer automatic inflation adjustments to account for market fluctuations.
10. Is high net worth insurance tax-deductible?
In many cases, premiums for high net worth insurance may be partially tax-deductible, depending on the type of coverage and jurisdiction. For example:
– Homeowners insurance (if the property is used for business purposes)
– Cyber liability insurance (if related to business activities)
– Kidnap and ransom insurance (if tied to professional risks)
However, personal insurance (e.g., for primary residences or personal vehicles) is typically not deductible. Policyholders should consult a tax advisor for specific guidance.
