
target net worth by age

Estimated Net Worth
$1.2 Million
Understanding net worth by age is a practical way to gauge financial progress, whether you’re comparing your own growth or analyzing how high-net-worth individuals build wealth. Target net worth benchmarks provide a framework for evaluating savings, investments, and asset accumulation at different life stages. While these figures are often based on averages or multipliers of income, they also reflect the strategies people use to grow their wealth—through careers, business ventures, and smart financial decisions. This article breaks down the concept of target net worth by age, using real-world examples to illustrate how wealth is built over time.
Net worth isn’t just about income; it’s the difference between what you own and what you owe. For many, hitting certain milestones by specific ages can mean the difference between financial security and uncertainty. Whether you’re just starting out or well into your career, knowing where you stand—and how others in similar positions have succeeded—can help you set realistic goals. Below, we’ll explore how net worth targets are structured, the paths people take to reach them, and the key factors that influence wealth accumulation.
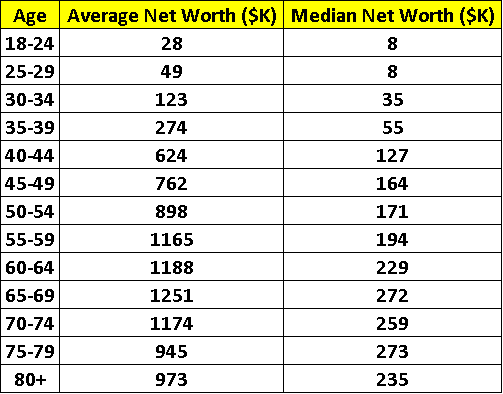
Target Net Worth by Age Net Worth in 2026
In 2026, discussions around target net worth by age often center on benchmarks that serve as financial checkpoints. For example, a common rule of thumb suggests that by age 30, your net worth should equal your annual salary. By 40, many financial advisors recommend having three to four times your annual income saved. These targets aren’t arbitrary; they account for compounding growth, career progression, and the ability to weather economic downturns. While these numbers are useful for planning, they also highlight how wealth disparities can widen based on career choices, investment strategies, and financial discipline.
For high-net-worth individuals, net worth by age often far exceeds these general guidelines. Someone in their 30s with a successful business or lucrative career might already have a net worth in the millions, while others in the same age group may still be paying off student loans or saving for a first home. The key difference lies in how assets are accumulated and leveraged. Real estate, stock portfolios, and ownership stakes in businesses are common drivers of wealth for those who surpass average benchmarks. In 2026, these targets remain relevant because they reflect the long-term impact of early financial decisions.
Career and Beginnings
Most people’s net worth journey starts with their career. Early financial habits—like saving a portion of each paycheck, avoiding debt, and investing in education—lay the foundation for future wealth. For many, the first decade of work is about establishing stability. Entry-level salaries may not allow for significant savings, but consistent contributions to retirement accounts and emergency funds can set the stage for growth. Those who prioritize high-income skills or industries with strong earning potential often see their net worth rise faster than peers in lower-paying fields.
The path to building net worth isn’t always linear. Some people switch careers, take pay cuts for better long-term opportunities, or pursue advanced degrees that temporarily reduce their savings. Others benefit from early career accelerators, like signing bonuses, stock options, or rapid promotions. The choices made in these early years—whether to rent or buy, how much to invest, and how aggressively to pay down debt—can have outsized effects on net worth by age 40 and beyond. Those who start businesses or freelance early often face more volatility but also gain the potential for higher returns.
Business Ventures & Assets
For many high-net-worth individuals, business ventures and asset ownership are the primary drivers of wealth. Unlike a salary, which has a ceiling, business equity and investments can grow exponentially. Real estate is a common starting point—rental properties, commercial buildings, or even a primary residence that appreciates over time. The key is leveraging assets to generate passive income or capital gains. Someone who buys a property in their 20s or 30s and holds it for decades can see their net worth multiply, especially in markets with strong appreciation.
Beyond real estate, ownership in private businesses or startups can dramatically increase net worth. Many entrepreneurs reinvest profits to scale their companies, rather than taking large salaries early on. This strategy can pay off if the business succeeds, as equity stakes often become more valuable than cash flow. Other assets, like stocks, bonds, or collectibles, also contribute to net worth growth. The most successful investors diversify their holdings to balance risk and reward. In 2026, digital assets like cryptocurrencies or online businesses are increasingly part of the conversation, though they come with their own set of risks.
Earnings and Income Streams
Net worth isn’t just about how much you save—it’s also about how much you earn and how you allocate those earnings. Multiple income streams can accelerate wealth building. A primary salary might cover living expenses, while side hustles, freelance work, or passive income from investments add to savings. High earners often maximize their income by negotiating raises, switching jobs for better pay, or developing skills that command premium rates. The more you earn, the more you can save and invest, assuming you avoid lifestyle inflation.
Passive income is particularly valuable for long-term net worth growth. Dividends from stocks, rental income from properties, or royalties from creative work can provide steady cash flow without requiring active effort. Those who focus on building passive income streams early often see their net worth grow faster than those who rely solely on earned income. In 2026, the gig economy and remote work have made it easier than ever to generate additional income, but discipline is required to direct those earnings toward assets rather than expenses. The most effective wealth builders treat income as a tool to acquire assets, not just fund spending.
Frequently Asked Questions About target net worth by age
1. What is a good net worth by age in 2026?
A good net worth by age in 2026 varies based on factors like income, location, and financial goals. General benchmarks suggest:
– Age 30: 1x your annual salary
– Age 40: 3x your annual salary
– Age 50: 6x your annual salary
– Age 60: 8x your annual salary
These are rough estimates, and individual circumstances may differ.
2. How do I calculate my net worth?
Net worth is calculated by subtracting your total liabilities (debts) from your total assets (cash, investments, property, etc.). The formula is:
Net Worth = Total Assets – Total Liabilities
Track your assets and debts regularly to monitor progress.
3. What is the average net worth for a 30-year-old in 2026?
The average net worth for a 30-year-old in 2026 is influenced by factors like student loans, housing costs, and savings habits. In the U.S., the median net worth for this age group is typically around $50,000–$100,000, while the average may be higher due to outliers.
4. How much should I have saved by age 40 in 2026?
By age 40 in 2026, financial experts often recommend having 3x your annual salary saved. For example, if you earn $80,000, aim for a net worth of $240,000. This includes retirement savings, investments, and other assets minus debts.
5. Is home equity included in net worth calculations?
Yes, home equity is included in net worth calculations. It’s calculated as the current market value of your home minus any outstanding mortgage balance. However, some financial planners exclude primary residences when assessing liquid net worth.
6. What is the ideal net worth for retirement in 2026?
The ideal net worth for retirement depends on your lifestyle and expenses. A common rule is the 4% rule, which suggests having 25x your annual expenses saved. For example, if you need $50,000 per year, aim for $1.25 million in net worth.
7. How can I increase my net worth quickly?
To increase your net worth quickly:
– Pay down high-interest debt
– Invest in appreciating assets (stocks, real estate)
– Increase your income through side hustles or career growth
– Live below your means and save aggressively
8. What is the median net worth for a 50-year-old in 2026?
The median net worth for a 50-year-old in 2026 is typically around $200,000–$300,000 in the U.S. However, this varies widely based on income, savings habits, and regional cost of living.
9. Should I focus on net worth or income?
Both matter, but net worth is a better long-term indicator of financial health. Income helps build net worth, but without saving and investing, high income alone won’t secure financial stability. Focus on increasing assets and reducing liabilities.
10. How does inflation affect net worth targets in 2026?
Inflation can erode the purchasing power of your net worth, so it’s important to adjust targets accordingly. If inflation averages 3% annually, a net worth goal of $500,000 in 2026 may need to be higher to maintain the same lifestyle in future years. Investing in inflation-resistant assets (stocks, real estate) can help.
