
what should my net worth be

Estimated Net Worth
$1.2 Million
Net worth is one of those financial benchmarks that people love to obsess over, but the truth is, there’s no one-size-fits-all answer. What your net worth should be depends on your age, career stage, lifestyle, and financial goals. Some people measure success by hitting arbitrary numbers, while others focus on stability, freedom, or leaving a legacy. The key isn’t just about how much you have—it’s about how well you’re managing what you’ve built and whether it aligns with where you want to be in the future. Whether you’re just starting out or decades into your career, understanding the factors that shape net worth can help you set realistic targets and make smarter financial decisions.
If you’re looking for a framework to gauge where you stand, this article breaks down the essentials. We’ll look at how net worth is calculated, what influences it, and how different income streams and assets play a role. The goal isn’t to compare yourself to others but to assess whether your financial trajectory makes sense for your life. By the end, you’ll have a clearer picture of what your net worth could—or should—look like in 2026, based on your circumstances.
What Should My Net Worth Be in 2026
Your net worth in 2026 will depend on several factors, including your age, profession, and financial habits. For most people, net worth is calculated by subtracting liabilities like debt from assets such as savings, investments, and property. If you’re in your 20s or 30s, your net worth might still be negative due to student loans or a mortgage, and that’s normal. By your 40s or 50s, however, you should ideally have a positive net worth that reflects years of saving and investing. Financial experts often suggest benchmarks like having twice your annual salary saved by age 40, but these are just guidelines.
The reality is that net worth varies widely. Someone in a high-earning field like tech or finance might have a significantly higher net worth than someone in a lower-paying profession, even if they’re the same age. Location also plays a role—living in an expensive city can inflate housing costs but also provide more earning opportunities. Instead of fixating on a specific number, focus on whether your net worth is growing over time. If you’re consistently saving, investing, and reducing debt, you’re on the right track, regardless of the exact figure.
Career and Beginnings
Your career path is one of the biggest determinants of your net worth. Early career choices, such as education, industry, and job stability, set the foundation for future earnings. For example, someone who starts in a high-demand field like software engineering or medicine will likely see faster net worth growth than someone in a lower-paying role. Even within the same industry, career progression matters—switching jobs for higher pay or taking on leadership roles can accelerate financial growth.
Starting early also gives you a significant advantage. Compound interest means that money saved in your 20s has decades to grow, while waiting until your 40s to start investing requires much larger contributions to catch up. If you’re just beginning your career, focus on building skills, increasing your income, and avoiding lifestyle inflation. The habits you form now—like consistent saving and avoiding unnecessary debt—will have a major impact on your net worth by 2026 and beyond.
Business Ventures and Assets
Assets are the building blocks of net worth, and diversifying them can protect and grow your wealth. Traditional assets include real estate, stocks, bonds, and retirement accounts, but business ownership can also play a major role. If you own a business, its value is part of your net worth, and successful ventures can significantly boost your financial standing. Even side hustles or freelance work can contribute if they generate consistent income or have sellable value.
Real estate is another key asset for many people. Owning a home can build equity over time, though it’s important to factor in mortgages and maintenance costs. Investment properties can provide passive income, but they also come with risks like market fluctuations and tenant issues. Beyond physical assets, digital assets like cryptocurrency or intellectual property (patents, royalties) are becoming more common. The key is to balance risk and liquidity—having assets that grow in value while still being accessible when needed.
Earnings and Income Streams
Your income is the fuel for your net worth, but not all income is created equal. A high salary is great, but if you’re spending most of it, your net worth won’t grow. Multiple income streams—like side businesses, rental income, or dividends—can provide stability and accelerate wealth building. Passive income, in particular, is valuable because it requires less ongoing effort. For example, royalties from a book or music, or dividends from stocks, can generate money without daily work.
Diversifying income streams also reduces risk. If one source dries up—like a job loss or a business downturn—others can keep you afloat. Many high-net-worth individuals have income from salaries, investments, and business ventures, which insulates them from financial shocks. If you’re relying solely on a paycheck, consider ways to add secondary income, whether through investments, freelancing, or creating digital products. The more sources of income you have, the faster your net worth can grow.
Frequently Asked Questions About what should my net worth be
1. What should my net worth be by age in 2026?
Your ideal net worth in 2026 depends on your age, income, lifestyle, and financial goals. A common benchmark is the “age-based net worth rule,” which suggests multiplying your age by your pre-tax income and dividing by 10. For example, if you’re 30 years old with a $60,000 salary, your target net worth would be around $180,000. However, this is a rough estimate—factors like debt, savings rate, and career stage play a big role.
2. How do I calculate my net worth?
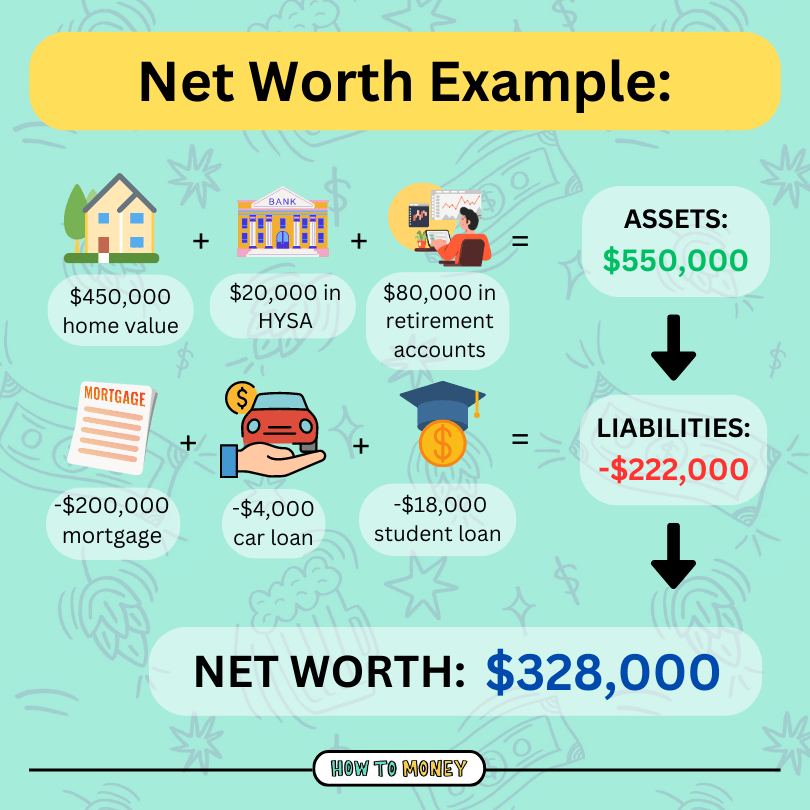
Net worth is calculated by subtracting your total liabilities (debts) from your total assets. Assets include cash, investments, real estate, retirement accounts, and valuable possessions. Liabilities include mortgages, student loans, credit card debt, and other loans. The formula is:
Net Worth = Total Assets – Total Liabilities
3. What is considered a “good” net worth in 2026?
A “good” net worth varies by individual circumstances, but general benchmarks can help. For example, the median net worth for U.S. households in 2026 is projected to be around $190,000 (adjusted for inflation). The top 10% may have a net worth exceeding $1.5 million, while the top 1% could surpass $12 million. However, these numbers depend on location, career, and financial priorities.
4. Should I include my home equity in my net worth calculation?
Yes, home equity should be included in your net worth calculation. Home equity is the difference between your home’s market value and any outstanding mortgage. However, remember that home equity isn’t as liquid as cash or investments, so it may not be readily accessible for financial needs.
5. How much should I have saved for retirement by 2026?
Retirement savings depend on your age and income. A common guideline is the “Fidelity rule,” which suggests having:
– 1x your salary saved by age 30
– 3x by age 40
– 6x by age 50
– 8x by age 60
– 10x by retirement
For example, if you’re 40 in 2026 and earn $80,000, you should aim for around $240,000 in retirement savings.
6. Does student loan debt affect my net worth?
Yes, student loan debt is a liability and directly reduces your net worth. For example, if you have $50,000 in assets but $30,000 in student loans, your net worth is $20,000. Paying down debt is a key way to improve your net worth over time.
7. What’s the difference between net worth and income?
Income is the money you earn (e.g., salary, bonuses, investments), while net worth is your total financial value (assets minus liabilities). Someone with a high income but significant debt may have a low net worth, while someone with modest income but strong savings could have a high net worth. Net worth is a better measure of long-term financial health.
8. How can I increase my net worth in 2026?
To grow your net worth, focus on:
– Increasing income (career growth, side hustles)
– Reducing debt (paying off high-interest loans)
– Saving and investing (retirement accounts, stocks, real estate)
– Avoiding lifestyle inflation (spending less than you earn)
– Building emergency savings (3–6 months of expenses)
9. Is there a net worth target for financial independence in 2026?
Financial independence (FI) typically requires a net worth that can cover living expenses without needing active income. A common rule is the “4% rule,” where you multiply annual expenses by 25. For example, if you spend $50,000 per year, you’d need a net worth of $1.25 million to be financially independent. Adjust this based on your lifestyle and risk tolerance.
10. What if my net worth is lower than the average for my age in 2026?
If your net worth is below average, don’t panic—focus on actionable steps to improve it. Start by tracking spending, paying down high-interest debt, and increasing savings. Small, consistent efforts (like investing even 5–10% of income) can significantly boost your net worth over time. Everyone’s financial journey is different, so prioritize progress over comparison.
